October 2, 2026

How She Built a $295,000 Kids Party Rental Side Hustle

Tayo Lanlehin from Bay Area Kids Rental

Buy it once, get paid for it over and over again — that’s a business model I never stop loving.

Tayo Lanlehin couldn’t find kid-sized tables and chairs for her son’s first birthday. So she ordered four styles from overseas, stashed them in her basement, and started an Instagram page(opens in new tab).

Four years later, BayAreaKidsRentals.com(opens in new tab) is a $295,000 business(opens in new tab) with ball pits, bounce houses, plushie-making stations, two 16-foot trucks, and a 3,500 square foot warehouse — and she still works a full-time job.

Here’s how she built it.

Tune in to Episode 755 of the Side Hustle Show to learn:

  • how to get your first rental clients through cold outreach
  • how to price rental items so they pay for themselves
  • how to build a team so the business runs without you

Download Your Free Bonus: 25 Other Unconventional Rental Ideas

25 Other Unconventional Rental Ideas

What else could you rent out for a profit? Here are some ideas!

Enter your email to download the full list now:

You’ll also receive my best side hustle tips and weekly-ish newsletter. Opt-out anytime.

Sponsors

quo ad banner

shopify logo(opens in new tab)

  • Gusto(opens in new tab) — Get 3 months free of the leading payroll, benefits, and HR provider for modern small businesses!

gusto payroll(opens in new tab)

indeed(opens in new tab)

monarch(opens in new tab)


How She Started a Kids Rental Business

Tayo was planning her son’s first birthday. The theme was “First Trip Around the Sun.”

“Kids are very visual,” she said. “You want to immerse them into a world of the theme that you’re going for.”

But when she went looking for furniture to match, all she could find were plain white plastic chairs. Nothing kid-sized. Nothing that fit a theme.

So she asked herself the question that starts most good businesses: What if I brought this to the Bay Area?

Starting With a $2,000 Inventory Test

She didn’t buy a warehouse full of product. She bought chairs.

Four styles, 20 of each, ordered from overseas — roughly $2,000. Storage was the empty 1,000 square foot basement in her house.

Then she set up an Instagram page and started emailing local event planners.

The planners wrote back fast — and immediately asked for packages that included tables. But when she didn’t have any, she bought tables, plus a few custom styles.

How to Get Your First Rental Clients

Tayo didn’t wait for demand to find her. Three moves did most of the work.

1. Naming the business after the search

When she was hunting for items herself, she didn’t even know what to call them.

So she asked what a parent would type into Google — and named the company Bay Area Kids Rentals.

2. Going straight to the people her customers already hire

She built a list of every event planner she could find online, followed them, and sent photos, a price list “like a menu,” and a short intro to herself and the business.

3. Shooting her shot with a big name

She emailed the wife of an NBA player, noticed her daughter’s birthday was coming up, and attached what she had.

The reply came the same day: I’m going to put you in touch with our event planner.

Later, that planner told her something better than a booking: “You were actually already on our radar.”

Why Event Planners Are the Best Customer in a Rental Business

Planners in her market run events from $500 to $80,000 for a single kid’s birthday(opens in new tab).

And before Tayo existed, they had a problem: they had to buy these items for clients, then figure out how to get rid of them afterward.

“We’re so glad you’re here,” one told her, “because now it can be sustainable, we can rent, and you also have different types of styles and a variety.”

One planner books dozens of parties a year. One happy planner is a pipeline.

The Instagram Strategy That Drives Bookings

Instagram is still her biggest source of leads and visibility. A few things made it work:

  • Her first post was an unboxing – “Look, Bay Area — we have kids tables and chairs now.”
  • She filmed her first event herself – Setup, party, the whole thing. It got a lot of views, because nobody had seen it before.
  • She collaborated on styled shoots with planners and venues, which got her tagged by vendors with real followings — and a few shoots into magazines.
  • Then the tagging snowballed – Planners tag her. Guests tag her. Other vendors tag her. Eventually people want to be on her page.

At nearly 10,000 followers, the account has become something more useful than a portfolio: Bay Area parents use it as an inspiration board and a vendor directory(opens in new tab).

New followers show up already seeing that half their kid’s friends’ parents follow her.

She learned the content habit in an earlier business — a travel experience company running trips in Africa, where she always brought a photographer and videographer. “If you didn’t take videos and pictures, did it actually happen?”

She also invested in SEO(opens in new tab), which sends leads directly to the site, where parents can book themselves.

The Referral Engine Nobody Talks About

Here’s the part that’s easy to miss: the guests at the party are your ideal customers.

Do something spectacular and different, and every parent in the room is going to ask who supplied it.

Tayo sees it in the data. A booking comes in from parents who work in one particular industry — and that same evening, three more bookings arrive from that same industry or neighborhood.

Rental Pricing: How to Know If an Item Will Pay for Itself

Chairs rent for around $10 each, with pricing subject to change.
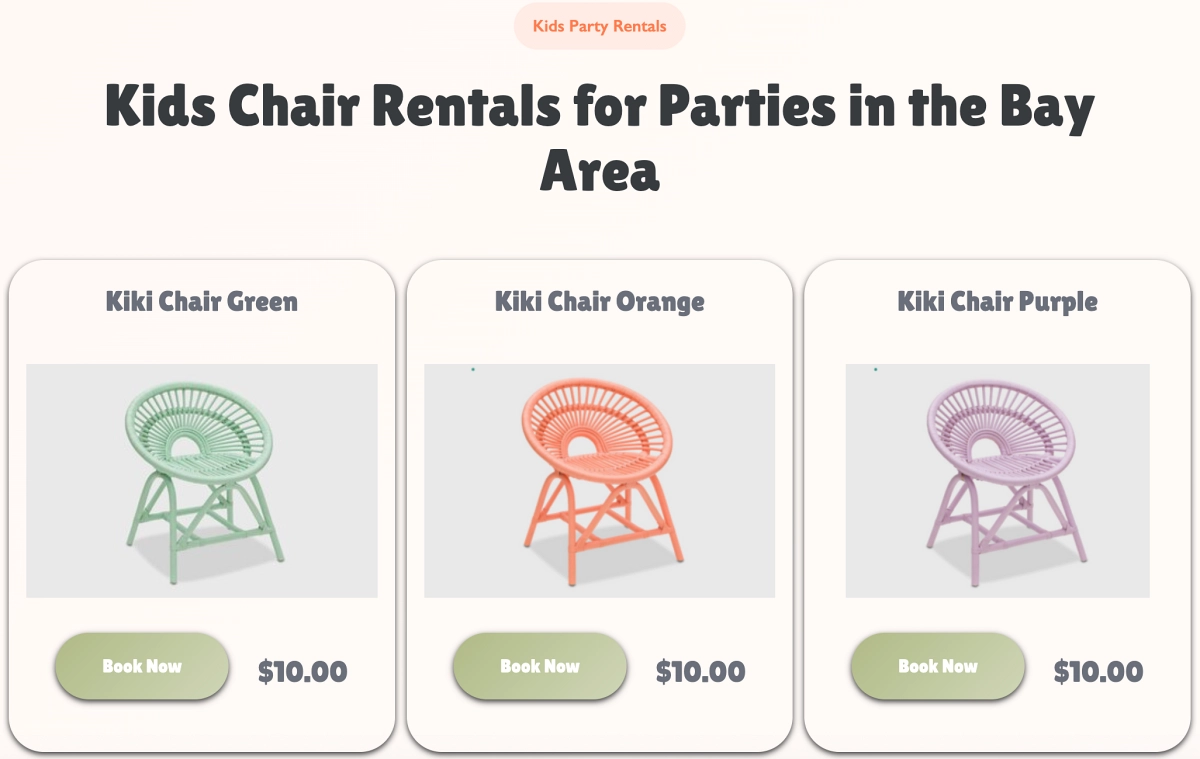
Kids Chair Rentals for Parties in Bay Area

Tayo’s goal is to earn back what she paid for an item in about six rentals. That’s before maintenance, which is a real cost when kids are involved.

Her items need to look Instagram-ready, so touch-up paint is an ongoing labor expense.

The good news is the shelf life. She says her garden bow chairs still look brand new after maybe 30 or 40 events.

Delivery: From Her Own Car to Two 16-Foot Trucks

  • Two events delivered in her own car — then, “okay, we need something else”
  • Hired a driver who had his own small truck
  • Added a transit van within a couple of months
  • Today: a transit van and two 16-foot trucks

She charges a delivery fee based on mileage, which covers running the vehicles and insuring them — and beats the hassle of renting a U-Haul(opens in new tab) every weekend.

Buying Inventory in Collections

Most of her inventory now gets released as collections. She studies trending party themes and color palettes, then buys tables and chairs to match.
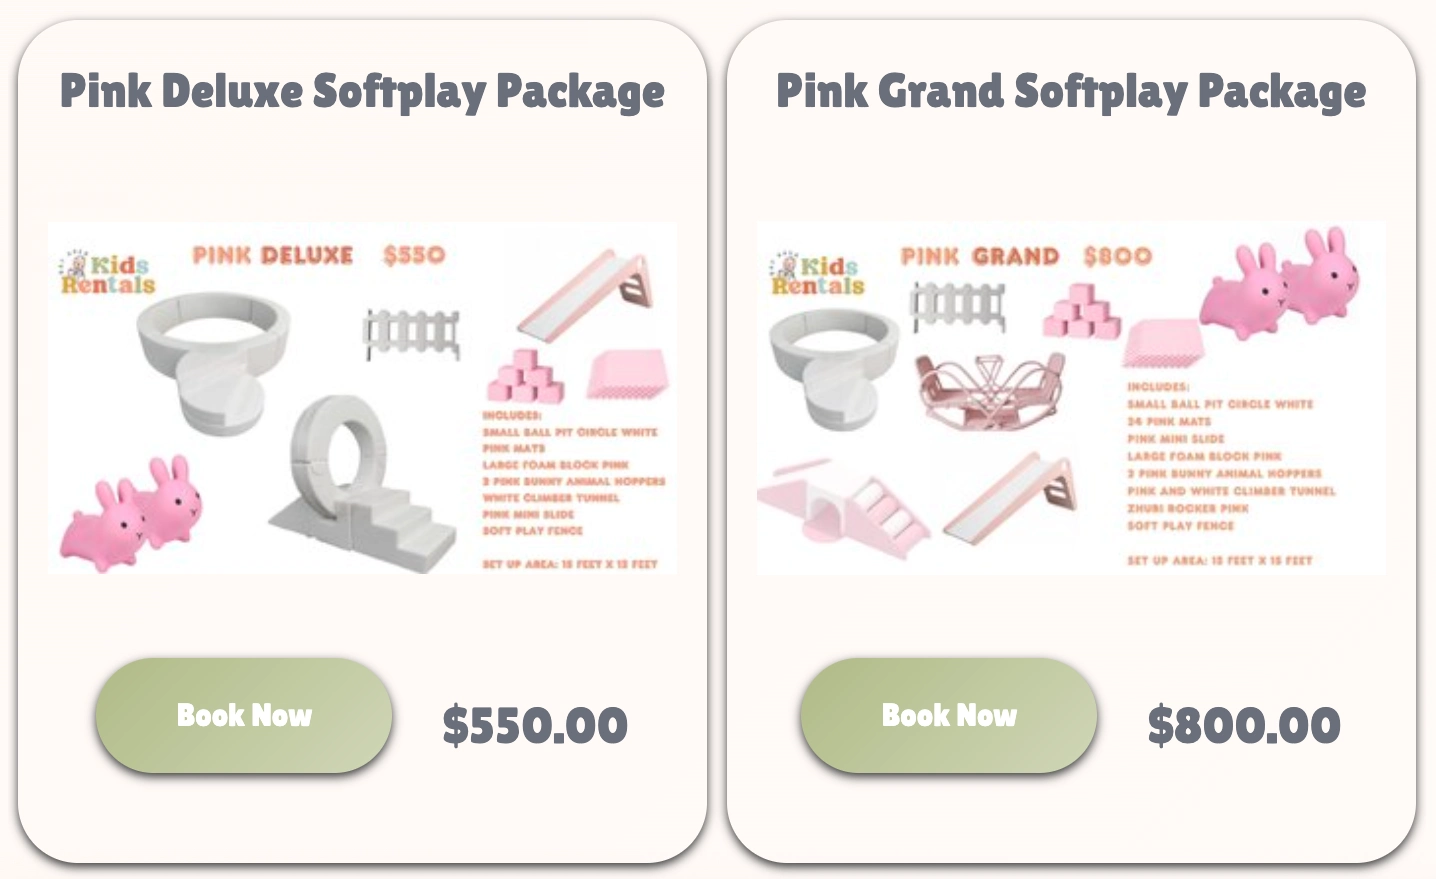
Softplay packages kids party rental

At the time we talked, camping themes were hot (think Parent Trap), Toy Story was back thanks to the new movie, and back-to-school was in season. Carnival themes never die.

Her star-shaped purple ball pit? Inspired by Taylor Swift parties.

She also uses a smart risk-reducer: because people book up to six months out, she lists new items on the website before they arrive. Demand shows up first, inventory second.

Expanding From Chairs to a One-Stop Party Shop

Clients kept asking: do you have bounce houses(opens in new tab)? Ball pits?
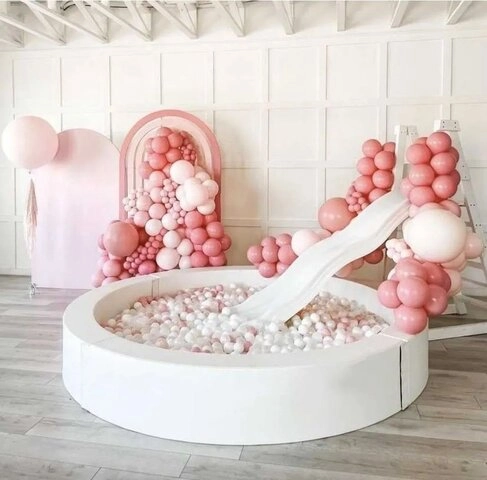
Large Ball Pit Circle from Bay Area Kids Rentals
From https://www.bayareakidsrentals.com/items/large_ball_pit_circle/

She couldn’t buy everything, so she prioritized. Ball pits came first — partly because she wanted to break into corporate “bring your kids to work” events. The two grand ball pits are big: one 13 feet across, the other roughly 13 by 10.

Then more ball pits, bounce houses in multiple colors, and customized activity workshops. The newest is a plushie-making setup — essentially Build-A-Bear on site, backdrop and all, where kids stuff their own plushie and decorate a T-shirt.

The reason is simple: busy parents want one vendor and one delivery. Less coordination for them, more rentals per booking for her.

Average booking now runs $1,000 to $1,500. Big ones hit $8,000 — a plushie workshop for 40 kids, plus a ball pit, plus tables and chairs.

Storage, Insurance, and Overhead

Adding inflatables(opens in new tab) raised her insurance costs a lot.

Storage grew fast too. Tayo went from the basement to a 1,200-square-foot warehouse behind her house to a commercial space of about 3,500 square feet that she moved into recently.

Payment terms help with cash flow: a 50% deposit to reserve the items, then the remaining balance one week before the event.

How She Runs It Around a Full-Time Job

Tayo has a manager, drivers, admin, and customer service assistants, and a social media manager. The team runs the business. She owns it.

That’s what makes a multi-six-figure operation survivable alongside a full-time job — especially in a business where the work happens on evenings and weekends, which is family time.

Her hardest problem isn’t demand. It’s hiring. “It’s been very, very tough to find just the right talent” — people who understand the aesthetics, the design-forward standard, the level of perfection this clientele expects.

Tools/Tech

Her husband is a CFO and handles payment processing.

What She’d Do Differently

Tayo would start with more items, sooner.

She began with only chairs, which meant guests could sit but couldn’t do anything else. If she started over, she’d go in with a one-stop-shop mindset from day one.

That doesn’t mean buying everything. A few chairs, a few tables, a few bounce houses, and a few ball pits would do it. People like packages, and they like dealing with one company.

Mistakes or Surprises?

Tayo shared two stories from opposite ends.

The good one: an early client’s grandfather was the CEO of Apple, and she got to meet him at his house. That’s when it hit her what kind of clientele the business was attracting.

The rough one: earlier this year, one of her trucks was stolen from her old warehouse. She walked in, saw the gate open, and the truck gone.

Insurance takes a while, so she bought a replacement truck to keep deliveries running. The original was eventually found. Now she has both, and she says she needs them.

What’s Next for Tayo?

Franchising(opens in new tab). She already has one franchise up and running and is vetting more operators.

Her take: if you find the right operator, you can grow much faster than trying to keep everything company-owned. She’d rather partner with people who are eager and ready to move than overthink the expansion.

“If you have the right operator as a franchise, you can really move much quicker.”

A brick-and-mortar party venue is also on the table, though that’s still in the analysis phase.

Tayo’s #1 Tip for Side Hustle Nation

“Try to understand the sector very well. Just start. Don’t overthink it. Bringing your own self into your work.”

25 Other Unconventional Rental Ideas

What else could you rent out for a profit? Here are some ideas!

Enter your email to download the full list now:

You’ll also receive my best side hustle tips and weekly-ish newsletter. Opt-out anytime.

Episode Links

Looking for More Side Hustle Help?

side hustle show cover art

The award-winning Side Hustle Show is the #1 side hustle podcast
with over 1,300 5-star ratings!
5-star rating

Listen in your favorite podcast app or directly in your browser.
listen on spotify
listen on overcast listen on podbean

Credit Card Rewards 101: How to Earn Free Cash and Travel by Spending Smarter

Over the last 15+ years, credit card rewards have earned my wife and I thousands of dollars in free money — in the form of cash, gift cards, and travel — just for buying the stuff we would have bought anyway.

credit card rewards

It’s not hard. We just put as much of our spending as possible on credit cards, and strategically sign up for new ones with attractive bonus offers.

And because we pay our balance in full every month, it’s all been at 0% interest.

Some say banks and credit card companies are evil.

I think they’re awesome.

You just have to be smart about how you use them.

In this free guide, I’ll outline:

  1. Why You Should Care About Credit Card Rewards
  2. How Credit Card Rewards Work (and why 1% cash back isn’t a great deal)
  3. How to Pick Which Cards to Apply For (and how often)
  4. How to Qualify for Business Credit Cards
  5. Credit Score Myths and Realities
  6. What’s in My Wallet and How I Track Cards
  7. Legit Ways to Meet Your Minimum Spending Requirements

You might not think of credit card rewards as a side hustle, but it’s been a profitable hobby of mine for years.

After all, every dollar counts!

Here’s how it works.

Credit Card Rewards: Why Should You Care?

Here are two reasons you should care about credit card rewards:

  1. Free money
  2. Free travel

Two of my favorite things!

In this free course, I’ll show you some easy ways to explode the cash back you’re probably currently earning on your spending.

On the travel front, points and miles from credit cards have helped my wife and I earn thousands of dollars in free travel and other benefits over the last few years.

We’ve visited Asia, several spots in Europe, Mexico, and all over the US.

It’s been said that travel is the only thing you buy that makes you richer — and plane tickets are still my favorite thing to buy — but it’s even more fun when you can buy them for free.

How Credit Card Rewards Work (and why 1% cash back isn’t a great deal)

Most credit cards offer some sort of cash back program, usually 1-2% on all purchases, but sometimes up to 5% for spending in certain categories.

This is the bank’s attempt to get you to pull out their card when you make a purchase — instead of all the others in your wallet.

That means if you spend an average of $1150 a month on charge-able purchases like food, gas, entertainment, and apparel (the national household average according to one report(opens in new tab)), you should be earning at least $138 a year in cash back rewards.

It’s obviously not a lifestyle-changer, but then again, it’s free money.

Still, You Can Do MUCH Better

Now if you divided that $13,800 in average annual spending among a few cards with attractive sign-up bonuses, you could earn the equivalent of $1000-2000 in rewards.

A heckuva lot better than $138!

For years, I had just one or 2 cards in my wallet, and would sit back and happily earn my 1-2% cash back. Knowing what I know now, it pains me to think of all the money I left on the table!

What do I mean? The magic really happens when you take advantage of certain sign-up bonuses for new cards — earning the equivalent of 20%, 30%, 40% cash back or more in travel value or statement credit.

Here’s just a really simple example:

The Chase Freedom® Flex℠ Credit Card(opens in new tab) is currently offering $200 as a sign up bonus when you spend $500 in the first 3 months. That’s 40% cash back, or probably 30x better than what you’re earning on your spending right now.

And if your household is anything like ours, it won’t be much trouble to spend $500 on your card in 3 months. Plus there’s no annual fee!

Click here to compare this card with others(opens in new tab).

In summary, 1%, pretty weak; 40%, we’re doing much better.

Now obviously there’s a bit of strategy involved since you can’t just go opening a new account every time you hit the $500 minimum. More on that below.

How (and How Often) to Pick Rewards Cards

Before you dive in, there are a few “rules” to keep in mind in this game.

The 3-Month Cooling Off Period

First, you don’t want to apply for credit cards in quick succession. Instead, I recommend waiting at least 3 months in between applications.

Each application is a note on your credit score. If you’re seen to be applying for too much credit in too short a window, it can raise a red flag — hurting your credit score and making it harder for your application to get approved.

Now, I’m not saying I’ve never broken this rule … but think of it as a general guideline or best practice.

The 5/24 Rule

The 5/24 rule(opens in new tab) is specific to rewards credit cards issued by Chase. It dictates you can’t open more than 5 accounts with Chase in a 24 month period.

The reason this one comes up is because Chase is one of the largest card issuers and has some of the most attractive cards.

Double Dipping

If you’ve been going after credit card rewards for awhile, you might want to apply for the same card you did in the past.

In most cases the banks are OK with this to try and win back your business, but each financial institution has different rules on whether or not you’re eligible for the sign-up bonus again, whether your current card needs to be cancelled, and how long it’s been since your last bonus.

(Probably not an issue if you’re just starting out, so I wouldn’t stress too much about it.)

How to Evaluate the Best Credit Card Rewards Offers

Like we’ve discussed, credit card rewards come in two main “flavors”: cash back and travel. But how do you know what’s a good deal and worth applying for?

Check the video to find out:

My Cash Back Card Recommendation for Starting Out

You can check out the current offers on cash back cards here(opens in new tab).

Credit cards like the Capital One Quicksilver Cash Rewards Credit Card(opens in new tab) offer a $200 sign-up bonus after you spend $500 in your first 3 months — with no annual fee. That’s up to 40% cash back!

capital one quicksilver 2025(opens in new tab)

Learn more here(opens in new tab).

If you know you’re gonna spend $500 in the next 3 months, that’s #freemoney. This card also gives you one of the highest cash back rates, with unlimited 1.5% back on every dollar you spend.

My Travel Card Recommendations

You can check out the current offers on travel cards here(opens in new tab).

Travel rewards credit cards come in 3 main categories:

  1. General — points and miles can be used across a variety of outlets (Issuers like Capital One, Chase).
  2. Hotel — points can be used at certain hotel brands (Marriott, Hilton, SPG, Hyatt).
  3. Airline — points can be used on certain airlines (Delta, American, Southwest).

Capital One Venture Rewards Credit Card

My favorite rewards card is the Capital One Venture card(opens in new tab), which offers “double miles” on all purchases. You can trade in your miles for statement credits, gift cards, or travel purchases.

capital one venture

Capital One is currently offering a 75,000 mile sign-up bonus (worth $750 in travel), after you spend $4,000 in the first 3 months. 

There’s a $95 annual fee.

Click here to learn more about this card and others(opens in new tab).

Chase Sapphire Preferred® Card

The Chase Sapphire Preferred® Card(opens in new tab) also has a strong bonus with 60,000 bonus points (worth over $750 when redeemed for travel) after spending $4,000 in the first 3 months. 

chase sapphire preferred(opens in new tab)

What’s cool about the Chase’s program is you can transfer points 1-for-1 to lots of travel partners including United and Southwest. (Or you can book directly through Chase’s rewards portal.)

There’s a $95 annual fee.

Click here to learn more about this card and others(opens in new tab).

Southwest Rapid Rewards® Priority Credit Card

For domestic travel, we’re all about Southwest.

In fact, one year we flew to Seattle, Chicago, Washington DC, Dallas, Orange County, Charlotte, and Las Vegas — all free on Southwest points.

sw priority credit card(opens in new tab)

The Southwest Priority Credit Card(opens in new tab) comes comes with a free Companion Pass® good through 2/28/26 plus 30,000 points after you spend $4,000 on purchases in the first 3 months from account opening.

(Those points alone are worth an estimated $450, and the Companion Pass could be worth thousands depending on how much you fly!).

This one comes with a $149 annual fee, which is offset by the $75 automatic travel credit issued on any Southwest purchase, and 7,500 bonus points on your cardholder anniversary (worth up to $112).

Click here to learn more about this card and others(opens in new tab).

How to Qualify for Business Credit Cards

As a side hustler, you’ve practically doubled your options for credit card rewards by being able to apply for business cards.

You already know you should be keeping your business income and expenses separate from your personal accounts, and a business credit card can help make that easier.

What Qualifies as a Business?

This probably doesn’t come as a shock, but to apply (and get approved) for a business credit card, you DO need a business.

Now if you’re side hustling, you’re probably already in business — even if it doesn’t feel like it.(opens in new tab)

If you ever do freelance work(opens in new tab), sell stuff on Ebay(opens in new tab), run a blog(opens in new tab), or do tutoring(opens in new tab), all of those could count as a business.

Do I Need to Register My Business?

By default, you’re already set up as a sole-proprietor. You don’t need to create an LLC or incorporate to apply for business credit cards.

Your business also doesn’t need to be profitable or even to have any revenue at all. Most startups have some expenses early on, and for better or worse, banks are often happy to lend you those startup costs.

(Of course, don’t spend money you don’t have.)

If you are “pre-revenue”, that’s OK. Just fill out the application as accurately and truthfully as possible!

Do I Need an EIN?

An EIN, or Employer Identification Number, is also not required to apply for business credit cards.

(Though it’s free to get one at IRS.gov(opens in new tab), and you may need one to open a business bank account.)

Most applications will ask for your social security number anyway.

My Recommended Business Credit Cards

You can check out the best current offers on business credit cards here(opens in new tab).

Chase Ink Business® Cash Credit Card

The Ink Cash card(opens in new tab) currently carries up to a $750 sign-up bonus after spending $6000 in the first 6 months.

($350 after spending $3,000 in your first 3 months; an additional $400 when you hit $6k in spend during your first 6 months.)

I like this one because there’s no annual fee, and you can earn up to 5% cash back on your first $25,000 in spending in certain common business categories.

chase ink business cash 2021(opens in new tab)

Click here to learn more and compare this card with others(opens in new tab).

Chase Ink Business Preferred® Credit Card

The Chase Ink Business Preferred card(opens in new tab) can earn you a 90,000 point sign-up bonus (worth $900 cash back or $1,125 toward travel when redeemed through Chase Travel℠), after a $8,000 minimum spend in the first 3 months.

chase ink business preferred 2021(opens in new tab)

Where it gets really fun though is this card offers 3x points on your first $150,000 in spending on travel and other select business categories like advertising. If you’re spending ad money on Facebook or Google, this will add up fast!

For instance, when I was running my shoe business(opens in new tab), I was spending $500-1000 a day on advertising, and racking up a ton of credit card points.

Click here to compare this card with others(opens in new tab).

Will This Hurt My Credit? Credit Score Myths and Realities

Applying for credit cards can impact your credit score, but probably not in the way you’re thinking.

There are a few main factors to consider, and I’ll address those below. However, the biggest thing is to be a responsible borrower: don’t spend money you don’t have, don’t max out your cards, and don’t pay late.

Inquiries

Each time you apply for a new credit card, that counts as a “credit inquiry” on your credit report.

Generally speaking, inquiries are OK, and each one will only ding your score perhaps 3 points. But too many inquiries in too short a time is a red flag to the banks and to your credit score.

Banks are risk-averse and to them, it’s like, “Whoa, why is this person suddenly in need of so much new credit?”

That’s why I recommend only applying for 1 card every 3 months.

Open Lines / Credit History

The longer you have an open credit account in good standing, the better.

That’s why keeping a card forever, especially one with no annual fee, can help your credit age.

Credit Utilization

Credit utilization is the amount you have charged divided by the amount you could charge. Basically, how much of your available credit line are you using?

This is where having multiple cards can actually help you.

Banks and credit monitoring services want to see low credit utilization — below 30% is a general guideline.

That means if you have $10,000 in available credit, but keep less than $3000 charged, you’ll be in good shape here. It’s a signal that you’re a responsible borrower — you have all this money available to you, but you only use a small portion.

My Actual Credit Score

I found a cool free service from Capital One called CreditWise(opens in new tab) that will give you your actual credit score for free, even if you’re not a Capital One customer.

Here’s what came back when I signed up:

So no, as long as you’re a responsible borrower and credit card user, you don’t have to worry about this harming your credit.

What’s in My Wallet and How Do I Track Cards?

I created a spreadsheet in Google Docs to help me keep track of the various credit cards I have, their benefits, and the annual fees.

You can save a copy for yourself here(opens in new tab). (Just be sure to hit File > Make a Copy, before you add any of your own info.)

How to Meet Your Credit Card Sign-Up Bonus Minimum Spending Requirements

If you plan ahead a little bit, it’s usually not hard at all to meet your minimum spending requirements.

Especially for the cash back cards(opens in new tab) we looked at — our family can easily find $500 worth of groceries, utilities, insurance, or other expenses.

Here are some of the common things we buy to meet the minimum spend:

  • Transfer over all recurring monthly payments — Internet, TV, cell phones, Netflix, life insurance, utilities.
  • Make the card your “daily driver” for every day expenses like gas and groceries.
  • Plan big purchases around new credit card sign-ups. That could be stuff like furniture or flights.
  • Group or family purchases. When you’re out to dinner with friends, offer to pick up the tab and have everyone give you cash.
  • Car repairs.
  • Medical expenses. With two young kids in the house (and an injury prone dad!), we sadly have had quite a few doctor bills lately!
  • Charity donations. Win win!

For business cards, here’s how I typically meet my minimums:

  • Recurring expenses like hosting and software
  • Contractor payments
  • Pre-paying for software or licenses
  • Conference registrations (and flights to those conferences)
  • Equipment like webcams, monitors, or a new laptop
  • Inventory purchases. My experiments with the Amazon FBA business were great for meeting minimum spend requirements!

The bottom line is to be intentional about using the new card and don’t sign up for something if you can’t see how you’ll reach the minimum spend required for the bonus.

Two Rules for Responsible Credit Card Rewards

1. Don’t spend money you don’t have.

2. Don’t buy crap you don’t need(opens in new tab).

Maybe this isn’t a truly entrepreneurial side hustle, but it does save me and my wife pretty significant money each year — dollars that go directly to our bottom line.

And that’s the same as earning more, right?

Refinance High Interest Debt

If you’re carrying credit card debt already, signing up for new credit cards probably isn’t for you. Instead, focus on paying back the debt first.

One resource that might be helpful is Credible(opens in new tab).

(opens in new tab)

The company has helped thousands of customers reduce their student loan payments, and they offer personal loans for debt consolidation as well.

How to Power Up Your Rewards

There are several apps that will give your credit card spending a free extra boost.

Among my favorites are:

Check out our full list of apps that pay you for more!

Your Turn

What’s in your wallet? Take action today and start working on a new sign-up bonus.

Once you learn about the offers and opportunities out there with credit cards — and start to reap the rewards — I think you’ll be as hooked as I am!

Pin it for later:

credit card rewards travel